Recession Panic Is Rising, but the Global Baseline Still Shows Growth

October 3, 2026 — Searches and market commentary about an “upcoming recession” have accelerated as government-bond yields rise, energy prices remain elevated and conflict threatens trade. The anxiety reflects genuine risks. It should not, however, be converted into a claim that a global recession has already begun.
The International Monetary Fund’s July World Economic Outlook Update projected global growth of 3.0% in 2026 and 3.4% in 2027. That is subdued and uneven, but it is growth. The IMF said technology demand was offsetting part of the drag from war while warning that disinflation had stalled and that renewed conflict or a sharp financial-market repricing could worsen the outlook.
Why the fear has intensified
September brought a heavy global bond sell-off. Higher government yields lift borrowing costs used to price mortgages, company debt and public financing. They can depress investment even without an immediate fall in output. Energy-importing economies also face a squeeze when oil and gas costs rise at the same time as credit becomes expensive.
The risks are not distributed evenly. The IMF projected 2026 growth of 2.3% for the United States, 0.9% for the euro area and 3.8% for emerging and developing economies as a group. A weak region, household or industry can feel recession-like pain even when the global aggregate remains positive.
Forecasts are scenarios, not guarantees
Economic forecasts change when wars, policy, inflation or financial conditions change. The IMF’s April severe scenario showed how prolonged energy disruption and tighter financial conditions could bring world growth close to the institution’s global-recession threshold. That scenario was a stress test, not a prediction.
Readers should watch confirmed indicators rather than viral certainty: employment, real household spending, industrial production, credit delinquencies, purchasing-manager surveys and inflation-adjusted income. Market prices can anticipate a downturn, but they can also reverse quickly when new data changes expectations.
For households, panic selling or taking expensive debt based on a recession headline can create harm before any downturn arrives. A more defensible response is to review emergency savings, variable-rate borrowing and concentration risk while avoiding promises that any asset or strategy is guaranteed to protect wealth.
The accurate conclusion is conditional: recession risk is elevated in parts of the world, and a new shock could materially worsen the outlook. Current global data and the IMF baseline do not establish that a worldwide recession is already under way.
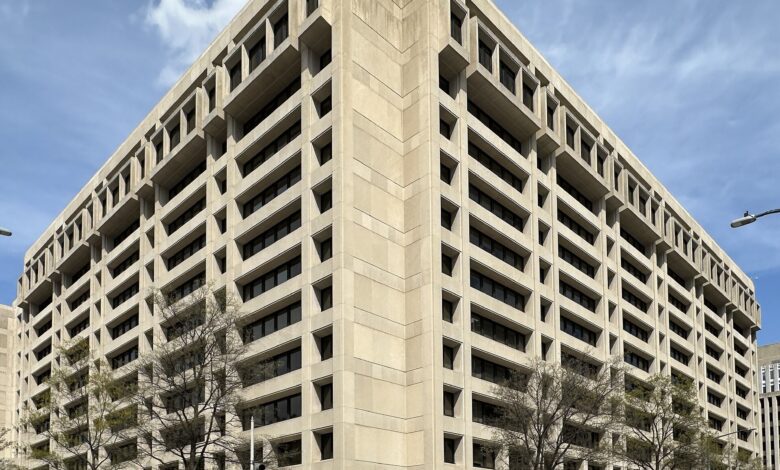
Image: IMF headquarters, Washington, March 2026. APK, CC BY 4.0.